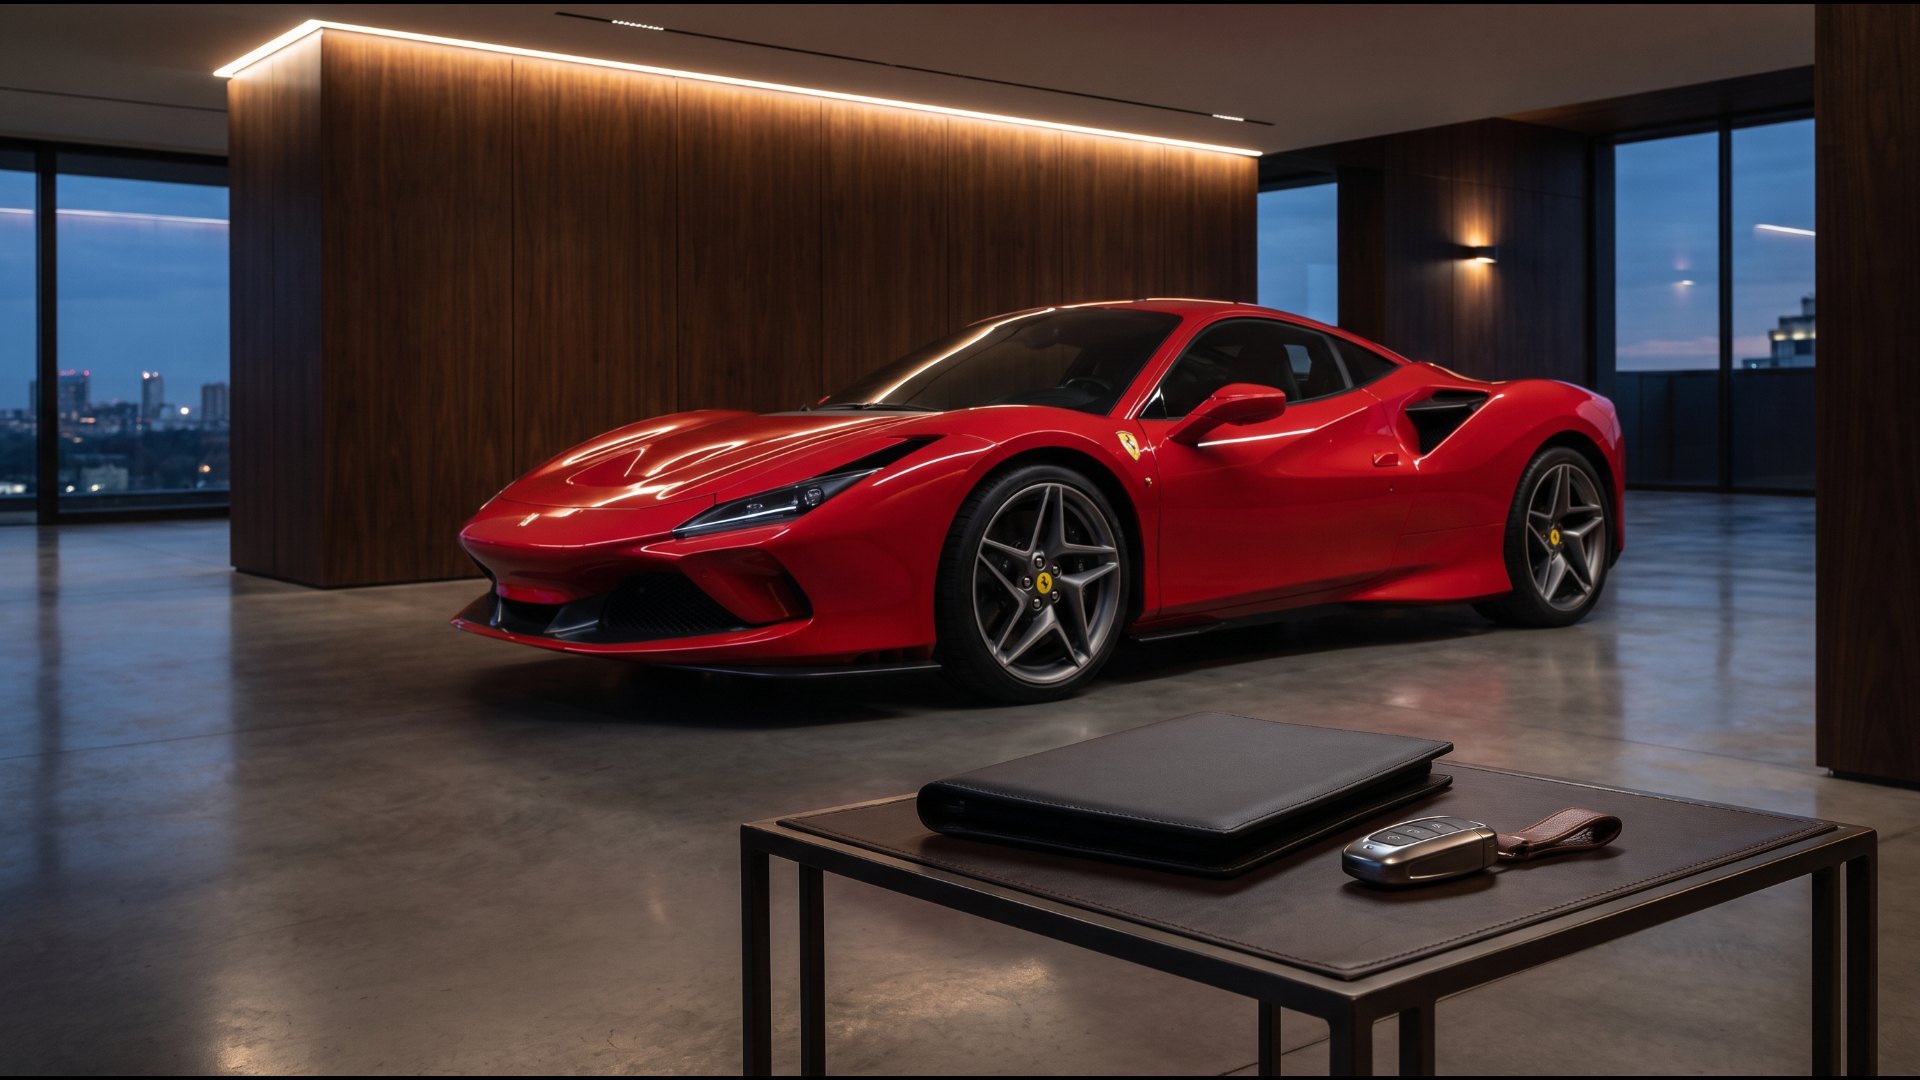
Imagine the moment. You have found the car: a hypothetical $250,000 Ferrari, the right color, the right options, a seller who has stopped pretending he will not sell. You say the four words every enthusiast rehearses in the shower. I’ll take it.
Then the real deal begins. The car is in a showroom in one state. The title may be in a lender’s file cabinet in another. Your money is in your bank, and nobody sensible wants to hand it over before the paperwork exists. (The price is illustrative, not a valuation.)
Here is the short version of how supercar deals actually work: agreeing on a price is the easy part. The less visible work is lining up four separate things—payment, ownership documents, condition and delivery—so that each one changes hands only when the others are ready. A small industry of brokers, escrow agents, lenders, inspectors and transporters exists to do exactly that. Digital checkout services are now folding several of those steps into one screen. None of them removes the need to read the agreement and inspect the car.
“Sold” is four events, not one
In everyday speech a car is “sold” when the handshake happens. In practice, a high-value deal has at least four distinct moments: the agreement (what, for how much, on what conditions), the payment, the transfer of ownership (the required ownership documents and lien releases, followed by applicable title and registration processing) and the physical handover. A dealer sale, a private sale and an online auction can put those moments in different orders, and the contract decides which order applies. There is no single universal closing process, which is precisely why the details matter.
The person selling it may not own it
Your first question is not about the car. It is about the person across the desk. Some cars on a showroom floor are owned by the dealer. Many expensive ones are consigned: the owner keeps title and pays a specialist to market and sell the car on their behalf. A car sitting under good lighting does not, by itself, prove who owns it or who has authority to sign it over.
The roles blur, so it helps to ask three plain questions. Whose interests do you represent? What are you authorized to agree to? How are you paid? A seller’s broker is working to get the consignor a good result. A buyer’s representative is hunting on your behalf. Some people act as go-betweens for both. Rules on licensing and duties vary by state, so clarify the broker’s role, compensation and obligations in writing; applicable state law may impose duties beyond the agreement.
Consignment terms are where the economics show. P1 Exotics, a New Jersey-based consignment specialist, publishes its own: as of October 13, 2026, its Consignment Concierge page lists a $500 listing fee and a 5% success fee on the final sale price, with a $2,500 minimum, and describes photography, marketplace advertising and coordination through to delivery. P1 Exotics is a dealer partner of ExoticMotors.com, ECN’s sister marketplace. That is one firm’s published schedule, not an industry rate. Other consignment agreements set different fees, decide who approves a price, who pays for detailing or transport, who insures the car while it waits, and how quickly the owner is paid after a sale.
Who gets the money first?
This is the oldest standoff in commerce. The seller will not release the car until paid. The buyer will not pay until the car and title are safe. Escrow is the classic fix: a neutral third party holds the money and releases it when conditions both sides agreed to are met.
Escrow is a contract about money, not a mechanical inspection and not a certificate of clean title. Escrow.com’s published process is a useful illustration. On its inspection-period page, buyer and seller agree an inspection window of 1 to 30 days at the start of the deal. After delivery, the buyer can accept or reject. If the buyer does nothing and the window lapses, the default is acceptance, and funds go to the seller. If the buyer rejects, the buyer pays shipping and insurance to send the item back, and the escrow fee is not refunded.
Two lessons hide in those terms. First, an acceptance window after delivery is not the same as a pre-purchase inspection before you commit. Sending a $250,000 car back across the country is expensive, so the serious inspection belongs before money moves. Second, the clock matters: an unattended window can close in the seller’s favor.
Then there is the lien. Plenty of expensive cars carry a loan, which means a lender holds the title or has its interest recorded on it. Clearing that requires a payoff figure from the lender, payment to the lender (not just the seller), and a lien release. Escrow.com, for example, sells a $60 lien-holder payoff service that confirms the payoff amount and sends the lender its check at closing, plus a separate $60 title-collection service for sellers with a clear title (prices as listed October 13, 2026).
Labels also deserve a second look. Escrow.com’s licensing page lists escrow licenses in some states and money-transmitter licenses in others, including an escrow license from California’s Department of Financial Protection and Innovation. A dealer’s deposit and a marketplace’s checkout are different arrangements again. The name on the payment page tells you less than the terms behind it.
Nor will a vehicle history report settle everything. The U.S. Justice Department’s NMVTIS consumer guidance describes its report as intentionally concise, covering a handful of fraud and theft indicators, warns that gaps can produce false negatives, and notes that a state’s full title record can hold information NMVTIS does not. No single report proves a car is free of liens or problems.
The expert toolkit is less glamorous than the car
Not every deal uses every specialist. But when a deal goes right, someone has usually done each of these jobs—and knows its limits.
| Task | Who or what | Helps establish | Does not establish |
|---|---|---|---|
| Pre-purchase inspection | Marque specialist | Diagnostics, condition photos, known model weak points | Anything outside the inspection’s scope or access |
| Provenance file | Owner, specialist, marque records | Build specification, service history, chain of ownership | Wrongdoing when records are missing; missing files are common |
| Valuation | Appraiser, price guides, completed sales | A reasoned range from comparable sales and condition | A guaranteed sale price |
| Closing paperwork | E-signature, ID checks, title and lien services | Who signed, what was agreed, when funds release | Unconditional protection; terms still govern |
| Handover | Enclosed transporter, condition report | The car’s recorded condition at pickup and delivery | That insurance covers every gap; transit and owner coverage are separate |
Values and insurance are their own rabbit hole; our explainer on how collector-car insurance decides what a car is worth covers that side in depth.
The money tools behind supercar deals
Back to our hypothetical buyer. Suppose they would rather not wire the full $250,000. Specialist finance offers several routes, and none of them is new.
Acquisition finance is simply a loan to buy the car. Collector-focused lenders stretch terms far beyond a typical car loan: Woodside Credit, a California-licensed lender founded in 2003, advertises terms of up to 15 years. RM Sotheby’s financing arm says on its financing page that it issues a non-binding term sheet to approved buyers shopping at auction or privately.
Longer terms lower the monthly payment, but the arithmetic cuts both ways. Take our $250,000 car with $50,000 down, financing $200,000 at an assumed 9% APR—an illustrative rate, not a quote:
| Term | Monthly | Interest |
|---|---|---|
| 72 mo. | $3,605 | $59,568 |
| 180 mo. | $2,029 | $165,136 |
The longer loan saves about $1,576 a month and costs roughly $105,568 more in interest, while keeping the debt alive for nine extra years. Whether the car rises, holds or falls in value over that time is a separate bet—and appreciation is never guaranteed to cover interest. Paying cash is not the wrong answer; it is just a different trade.
Consignment advances run the other direction, for sellers. RM Sotheby’s says an approved consignor can receive up to 60% of a car’s estimated hammer price when signing the consignment agreement, with the advance deducted from sale proceeds. That is money borrowed against a future sale, not extra money. If the car fails to sell, the agreement—not optimism—decides what happens next.
Equity release lets an owner borrow against cars already in the garage without selling them. RM Sotheby’s describes loans secured against a single car or a collection. Its public page does not spell out custody or driving terms, and lenders differ: some collateral loans require the car to be stored with the lender, others do not. Ask before assuming you keep the keys.
What is actually changing: the one-screen closing
The important development is integration. Bring a Trailer’s Verified Checkout, run with the transaction company Caramel, shows how much of the old relay race can be compressed into one online flow. According to Caramel’s Verified Checkout page, it verifies buyer and seller identity, generates the paperwork, holds the buyer’s funds, pays off a seller’s existing loan, and handles title and registration. Buyers can also add financing, insurance, a service contract and transport.
Its structure is different from classic escrow. Caramel says that when both parties sign, the seller is actually selling the car to Caramel and the buyer is buying it from Caramel, which operates as a licensed dealer to complete the sale, title transfer and registration. Caramel coordinates payment with vehicle pickup and title receipt; sellers should confirm the applicable release schedule in their transaction terms. As of October 13, 2026, Caramel lists a $149 fee for full title and registration service, requires wire payment on transactions of $40,000 or more, and requires a U.S. driver’s license and phone number.
Notice what is not on that list: an inspection of the car. Digital closing tidies the money and the paperwork. Condition is still the buyer’s job. And specialty loans, private sales and consignment advances are long-established tools; what has changed is how neatly they can now be bundled.
Back to the Ferrari
Our imaginary buyer has not taken delivery yet, and we will not pretend to know how it ends. But a well-built deal answers five questions before the transporter arrives. Who owns the car? Who has authority to sell it? Who holds the money? What, exactly, releases it? And at what moment does responsibility for the car move from one person to the other?
Those answers rarely make the photo at the handover. They are why the photo can happen at all. The paperwork is not the opposite of the fun part of owning a supercar. Done right, it is what lets you stop thinking about the deal and start thinking about the first drive. If you are curious why some cars change hands in days while others linger for months, our look at exotic-car market liquidity picks up where this leaves off.
Provider terms cited in this article were checked on the providers’ own pages on October 13, 2026, and can change. This article is general information, not legal or financial advice.